ACCA Qualified Accountants
9 Powick Road, Birmingham B23 7NY
Tax Brackets UK Explained (2026/27 Guide)
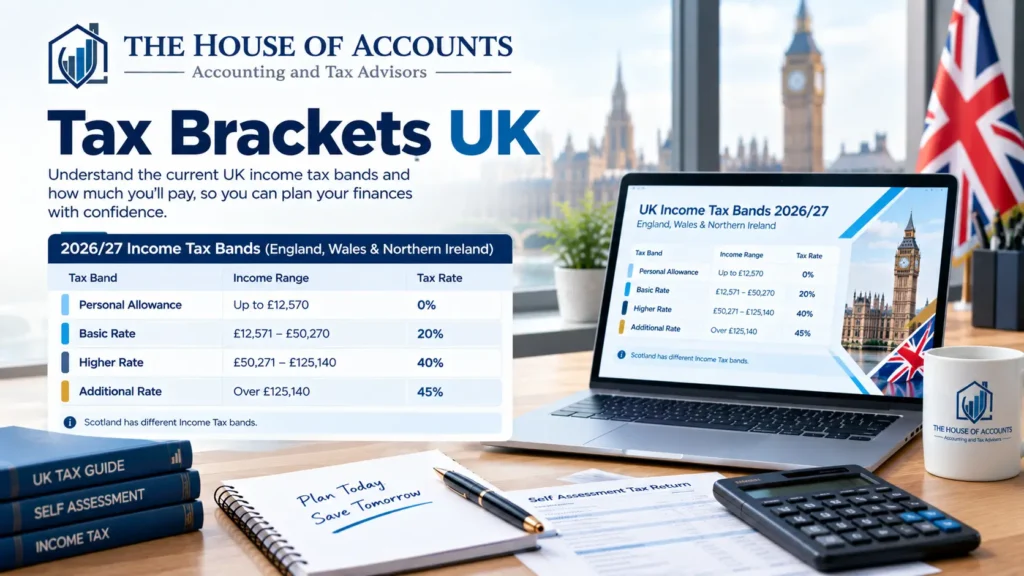
Understanding exactly which tax bracket your income falls into helps you plan pay, pensions, and business decisions with confidence. House Of Accounts breaks down the 2026/27 tax brackets UK taxpayers need to know.
UK Tax Brackets for 2026/27
- Personal Allowance: £0 to £12,570 — 0% tax.
- Basic rate: £12,571 to £50,270 — 20% tax.
- Higher rate: £50,271 to £125,140 — 40% tax.
- Additional rate: above £125,140 — 45% tax.
These thresholds apply to England, Wales, and Northern Ireland. Scotland uses its own six-band system with different rates and thresholds for non-savings, non-dividend income.
How the Bands Actually Work
UK Income Tax is layered, not a flat rate applied to your whole income. You only pay the higher 40% rate on the portion of income that falls above £50,270 — everything below that threshold is still taxed at the lower rates. Moving into a higher band never reduces your overall take-home pay, since only the excess is taxed at the higher rate.
The Personal Allowance Taper
Once adjusted net income exceeds £100,000, the £12,570 Personal Allowance reduces by £1 for every £2 earned above that point, disappearing entirely at £125,140. This creates an effective marginal tax rate of around 60% on income between £100,000 and £125,140 — often called the “tax trap” by accountants, since it’s frequently overlooked.
Dividend Tax Bands
If you receive dividend income, it sits on top of your other income for band purposes but is taxed at separate, lower rates than salary — relevant for company directors deciding how to structure their pay between salary and dividends.
National Insurance Alongside Income Tax
Employee National Insurance is charged separately from Income Tax, at 8% on earnings between the primary threshold and the upper earnings limit, and 2% above that. Together, Income Tax and NI determine your true overall tax burden at any given salary level.
Reducing Your Effective Tax Rate
- Pension contributions reduce your adjusted net income, potentially avoiding the £100,000-£125,140 taper.
- Salary sacrifice schemes can lower taxable income while maintaining overall compensation.
- For directors, balancing salary and dividends can reduce overall tax versus salary alone.
Historical Context: How Brackets Have Changed
The Personal Allowance and higher-rate threshold have been frozen since 2021/22, a policy commonly referred to as “fiscal drag.” Rather than actively raising taxes, freezing thresholds while wages rise with inflation gradually pulls more people into higher tax bands over time, without any headline rate ever technically increasing. This freeze is currently legislated to continue for several more years, meaning more taxpayers are likely to cross into the 40% band even without any change to their real income.
- The Personal Allowance has been frozen at £12,570 since 2021/22.
- The higher-rate threshold has similarly been frozen at £50,270 over the same period.
- Fiscal drag means real incomes need not rise much before crossing into a higher band.
This matters most for anyone receiving an annual pay rise roughly in line with inflation — on paper, income is keeping pace with the cost of living, but because the tax bands themselves aren’t moving, a growing share of that income gets taxed at the higher rate over time. Understanding this dynamic is genuinely useful when negotiating pay or reviewing pension contributions, since it explains why take-home pay can feel like it’s falling behind even when gross salary is technically rising each year.
For business owners and company directors, knowing exactly where personal income sits against these brackets is especially valuable when deciding how much to draw as salary versus dividends, or how much to leave in the company for the following year. A well-timed decision — informed by which bracket the next pound of income would fall into — can meaningfully reduce the overall tax paid across a business and its owner combined.
Plan Your Tax Position With Confidence
Understanding which bracket you sit in is the first step — our tax planning services go further, helping you structure income efficiently across salary, dividends, and pension contributions.
Frequently Asked Questions
0% up to £12,570, 20% from £12,571 to £50,270, 40% from £50,271 to £125,140, and 45% above £125,140, for England, Wales and Northern Ireland.
No. Scotland uses its own six-band system with different rates and thresholds for non-savings, non-dividend income, set by the Scottish Government.
No. Only the portion of income above £50,270 is taxed at 40% — income below that threshold remains taxed at the lower rates.
It refers to the effective marginal rate between £100,000 and £125,140, caused by the Personal Allowance tapering away alongside 40% tax being charged on the same income.
Yes. The Personal Allowance and higher-rate threshold have been frozen since 2021/22 and are currently legislated to remain frozen for several more years, pulling more people into higher bands as wages rise.
Pension contributions or Gift Aid donations can reduce your adjusted net income below £100,000, restoring some or all of your Personal Allowance.
Yes. Our accountants provide tax planning advice tailored to your income level, helping you structure earnings as efficiently as possible.
Ready to Start?
Don’t let confusing numbers or missed deadlines hold your business back. Get matched with a dedicated ACCA Qualified accountant at House Of Accounts and get clear, upfront pricing from day one.
Get in touch with our team today and let us take the accounting stress off your plate.
Contact Us to Book Your Free Consultation
📞 Call: +44 20 3386 1902
💬 WhatsApp: +44 7539 945628
✉️ Email: Info@housesofaccounts.co.uk
📍 Address: 9 Powick Road, Birmingham, B23 7NY, UK